A medical university with 1,050 beds. Over a thousand students. 190 faculty. Annual salary expenditure of ninety-one crore rupees.
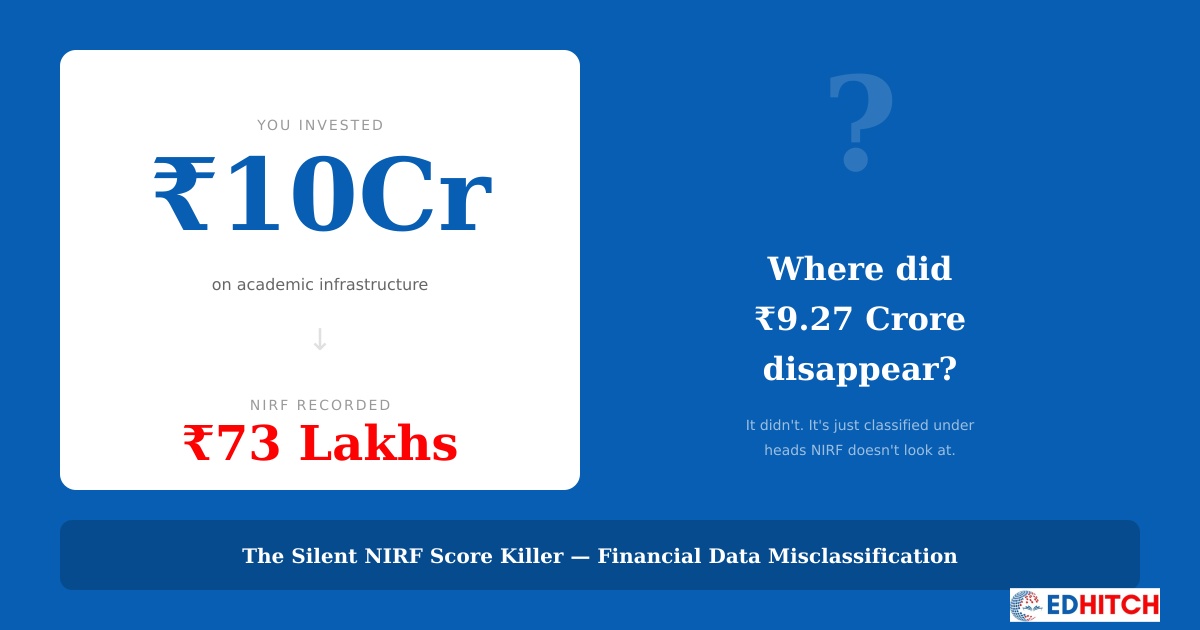
Their total capital expenditure reported to NIRF? Seventy-three lakhs.
Read that again. A teaching hospital with a thousand beds, running departments across medicine, surgery, paediatrics, orthopaedics, and a dozen specialities — reporting less capital investment than a mid-tier coaching centre.
The institution wasn't lying. They weren't hiding expenditure. They were simply classifying it under accounting heads that NIRF doesn't look at.
This is the most common — and most damaging — data problem we find in NIRF diagnostics. Institutions that spend crores on infrastructure but report lakhs to NIRF. Not because they don't invest. But because their accounts department and their NIRF portal speak different languages.
How NIRF reads your financial data
NIRF evaluates financial resources under the TLR parameter — Teaching, Learning and Resources. This parameter carries 30% weightage in your final NIRF score.
Within TLR, two sub-parameters use financial data directly:
FRU (Financial Resources and their Utilisation) — 30 marks. This measures your total operational expenditure per student. It includes salaries of teaching and non-teaching staff, maintenance of academic infrastructure, and spending on seminars, conferences, and workshops. The more you spend per student on operations, the higher your FRU score.
Capital expenditure per student is calculated from a separate section of the NIRF data capture system. NIRF asks for three specific categories of capital spending.
That's it. Two financial measurements. Both calculated per student. Both directly impacting TLR — which is 30% of your total score.
The three capital expenditure heads NIRF counts
NIRF asks institutions to report capital expenditure under exactly three heads:
1. Library. This includes purchase of books, journal subscriptions, and e-resource subscriptions. Physical books, digital databases, and online journal access all count here.
2. New Equipment for Laboratories. This includes any new equipment purchased for teaching and research laboratories during the reporting year.
3. Other expenditure on creation of Capital Assets. This is a catch-all for other academic capital spending — but it explicitly excludes expenditure on land and buildings.
That's the entire capital expenditure section. Three lines. Three numbers. NIRF adds them up and divides by the number of students.
If your institution spent ten crore on capital assets but classified nine crore under heads that don't map to these three categories — NIRF sees one crore. Your capital expenditure per student drops by 90%.
Where the money disappears
Here's what actually happens at most institutions.
The accounts department maintains a chart of accounts designed for statutory audit, income tax compliance, and regulatory reporting. These accounts are structured around accounting standards — not around NIRF's three capital expenditure heads.
When the NIRF portal opens, someone from the IQAC or the administration asks the accounts department: "How much did we spend on library, lab equipment, and other capital assets?"
The accounts department looks at their chart of accounts. They find a head called "Library" — and report whatever is there. They find something that looks like "Laboratory Equipment" — and report that number. For "Other Capital Assets," they often report whatever doesn't fit the first two.
The problem? The accounts department's classification and NIRF's classification are not the same thing.
Here are the most common mismatches we find:
Clinical equipment at medical institutions. Imaging machines, surgical instruments, diagnostic equipment — these are often classified under "Hospital Equipment" or "Medical Equipment" in the accounts. But NIRF's "New Equipment for Laboratories" doesn't distinguish between a chemistry lab and a clinical lab. If the equipment is used for teaching or research, it should count. But if the accounts head says "Hospital Operations," the NIRF team doesn't include it.
IT infrastructure. Computers, servers, projectors, smart boards, simulation software — often classified under "IT Assets" or "Office Equipment." But if these are used in classrooms and labs, they could fall under NIRF's "Other Capital Assets."
Library e-resources. Many institutions have shifted from physical books to digital databases — Scopus access, journal subscriptions, online learning platforms. These are sometimes classified under "Subscription Services" or "Software Licenses" in the accounts — not under "Library." NIRF doesn't see them.
Furniture and fixtures for academic spaces. New furniture for classrooms, seminar halls, laboratories — sometimes classified under "Furniture" as a general category rather than under academic capital. If the furniture is for academic use, it belongs in NIRF's third head.
Research equipment. Equipment purchased specifically for research projects — sometimes classified under the project head or under "Sponsored Research" rather than under laboratory equipment. The equipment exists. It's in the lab. But the accounts classification doesn't put it where NIRF looks.
The operational expenditure problem
Capital expenditure gets the most attention because the misclassification is dramatic. But operational expenditure has its own issues.
NIRF's FRU sub-parameter counts three types of operational spending:
1. Salaries — teaching and non-teaching staff. This is usually reported correctly because it's a large, obvious number.
2. Maintenance of academic infrastructure — consumables, lab running costs, equipment maintenance. But NIRF explicitly excludes maintenance of hostels, rent, and depreciation. If your accounts department includes hostel maintenance in the same head as academic maintenance, the number is inflated. If they exclude lab consumables because those are under a different head, the number is deflated.
3. Seminars, conferences, and workshops. This includes spending on organising academic events, faculty travel to conferences, and workshop expenses. Some institutions classify conference travel under "Travel and Conveyance" instead of under academic events. NIRF doesn't count travel. It counts seminars.
Your accounts department optimises for tax and audit. NIRF optimises for ranking. The same rupee, classified under different heads, produces different NIRF scores.
Real numbers from real institutions
We won't name institutions. But here are patterns we've observed across diagnostics:
A medical university reporting total capital expenditure of under one crore — while their hospital purchased imaging equipment worth several crore in the same year. The equipment was classified under hospital operations.
An engineering college reporting zero library expenditure for one year — not because they stopped buying books, but because that year they shifted to e-resources, which were classified under "Software Subscriptions."
A management institution where MDP and consultancy revenue collapsed by 90% in the NIRF data — not because the activity stopped, but because the revenue was reclassified under a different accounting head after a change in auditors.
A pharmacy college where lab equipment spending showed fifty-three thousand rupees — for an institution with twelve laboratories. The actual equipment purchases were under a departmental head that didn't map to NIRF's category.
In each case, the institution's actual investment was much higher than what NIRF saw. The gap wasn't fraud or underinvestment. It was classification.
Why this matters more than you think
Let's do the maths.
TLR is worth 30% of your total NIRF score. Within TLR, FRU is worth 30 marks out of 100. That means FRU alone contributes up to 9 points to your final score.
Capital expenditure per student is factored into the overall TLR assessment. If your capital expenditure looks unusually low compared to peer institutions, it pulls down your TLR score.
Now compare: a medical college reporting seventy-three lakhs capital expenditure versus a peer institution correctly reporting seven crore. Both may have spent similar amounts. But one looks like it invests in academic infrastructure. The other looks like it doesn't.
NIRF is a comparative ranking. Your score isn't measured in isolation — it's measured against every other institution in your category. If your peers are classifying correctly and you aren't, you're not just losing marks. You're losing rank positions.
What you should check before next year's submission
If your institution has submitted NIRF data this year and you're not sure whether the financial numbers are right, here are the questions to ask your accounts team:
First, pull out your chart of accounts. List every head under which capital expenditure was booked in the last three years. Then ask: which of these are academic in nature? Which involve equipment, books, or infrastructure used for teaching and research?
Second, compare the total capital expenditure in your NIRF submission with the total capital expenditure in your audited balance sheet. If the NIRF number is less than 30% of the balance sheet number, you almost certainly have a classification gap.
Third, look at the trend. Did any capital expenditure category show zero in any year? Did any category drop by more than 50% year-on-year? A sudden zero or a dramatic drop usually means the expenditure moved to a different accounting head — not that the spending stopped.
Fourth, check if your operational expenditure excludes items it should include — or includes items it shouldn't. Conference spending under "Travel." Lab consumables under "General Maintenance." Hostel costs mixed with academic maintenance.
The goal is not to inflate numbers. The goal is to ensure that what you actually spend is accurately reflected in what NIRF sees. If you invest in academic infrastructure, NIRF should know about it.
The fix is not expensive
Reclassifying financial data for NIRF doesn't require changing your accounting system. It doesn't require new software. It doesn't even require changing how your accounts department works day-to-day.
What it requires is a mapping exercise — a one-time effort where someone sits with the accounts team and maps each relevant accounting head to NIRF's financial categories. Once the mapping exists, extracting the right numbers for NIRF becomes a straightforward exercise every year.
Most institutions can complete this mapping in a single working day. The impact on their NIRF score can be measured in points — not fractions of a point.
The mapping itself requires understanding both the institution's chart of accounts and NIRF's specific definitions. It's a specialised exercise, but not a complicated one.
We Cover Financial Data Strategy in Detail
Session 5 of our 5-Day programme walks through financial classification mapping for NIRF — with live examples and a reclassification checklist you can use with your accounts team.
April 6-10, 2026 · Mon-Fri · 7-9 PM · Online · NAAC 6.3.4 Certified
Register Now — ₹2,499 →Frequently Asked Questions
What financial data does NIRF ask for?
NIRF asks for capital expenditure (library, lab equipment, other capital assets excluding land and buildings) and operational expenditure (salaries, maintenance, seminars). Both are used to calculate FRU and capital expenditure per student under TLR.
Why is my institution's NIRF capital expenditure so low?
In most cases, the actual investment is much higher than the NIRF submission shows. The problem is classification — equipment, subscriptions, and teaching infrastructure classified under accounting heads that don't map to NIRF's three capital categories.
What is FRU in NIRF?
FRU (Financial Resources and their Utilisation) is a sub-parameter under TLR worth 30 marks. It measures total operational expenditure per student — salaries, maintenance, and seminar spending. Higher spending per student means a higher score.
What counts as capital expenditure in NIRF?
Three categories: Library (books, journals, e-resources), New Equipment for Laboratories, and Other Capital Assets (excluding land and buildings). Hostel construction, building renovation, and depreciation are excluded.
Can reclassifying financial data improve my NIRF score?
Yes. If expenditure is classified under heads NIRF doesn't recognise, reclassifying into NIRF's categories can sharply improve the TLR score. This requires mapping your chart of accounts to NIRF's financial heads — a one-time exercise.
How much can financial data affect the NIRF score?
FRU is worth 30 marks within TLR, which carries 30% weightage. Financial data can influence up to 9 points on your final 100-point NIRF score. In a comparative ranking, that can shift your position by dozens of ranks.

Edhitch Advisory
Accreditation & Ranking Intelligence · NAAC · NBA · NIRF · 12 Years · 100+ Institutions